Budget 2027 raises the monthly tax-free threshold from Rs 150,000 to Rs 162,500
Budget Speech 2027 raises the monthly tax-free threshold to Rs 162,500 from 1 April 2027. VAT on foreign-currency supplies will use the CBSL indicative rate.
BuiltList3 min read
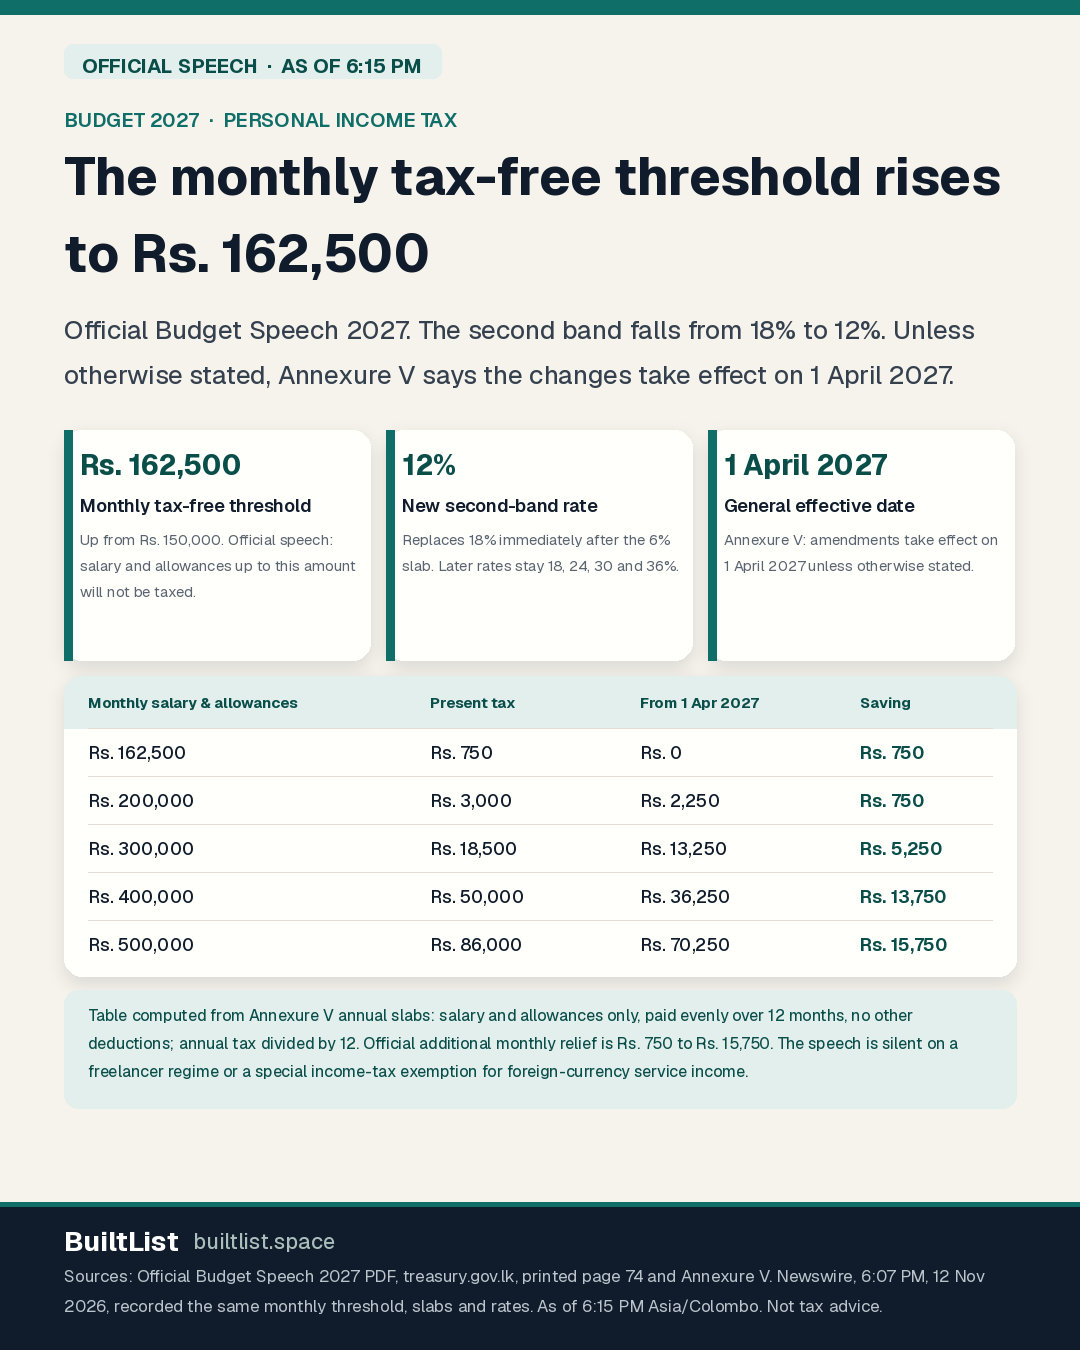
The official Budget Speech 2027 revises personal income tax. The English text (printed page 74) says the monthly tax-free threshold, already raised from Rs. 100,000 to Rs. 150,000, “will be further increased to Rs. 162,500.” “A person receiving a monthly salary and allowances of up to Rs. 162,500 will not be required to pay tax on his or her salary.” The 6 percent slab will be Rs. 70,833 a month; later slabs widen from Rs. 41,667 to Rs. 50,000. Rates will be 6, 12, 18, 24, 30 and 36 percent, “applying a rate of 12 percent instead of 18 percent after the 6 percent rate.” The top rate will start at Rs. 433,000 a month, up from Rs. 358,000. Additional monthly relief is officially “a minimum of Rs. 750 to a maximum of Rs. 15,750.”
Annexure V states the same change annually: relief rises from Rs. 1.80 million to Rs. 1.95 million. Unless otherwise stated, the amendments take effect on 1 April 2027. At 6:07 PM Asia/Colombo, Newswire recorded the same monthly threshold, slabs and rates, but not the official relief range or that date.
A worked comparison, from the official annual slabs
Assumptions: Annexure V’s present and revised annual bands; salary and allowances only, paid evenly over 12 months; no other deductions; annual tax divided by 12. Under those assumptions the official Rs. 750 to Rs. 15,750 monthly relief is reproduced exactly. Illustrations only, not a PAYE calculator.
| Monthly salary and allowances | Present monthly tax | Monthly tax from 1 April 2027 | Monthly saving |
|---|---|---|---|
| Rs. 162,500 | Rs. 750 | Rs. 0 | Rs. 750 |
| Rs. 200,000 | Rs. 3,000 | Rs. 2,250 | Rs. 750 |
| Rs. 300,000 | Rs. 18,500 | Rs. 13,250 | Rs. 5,250 |
| Rs. 400,000 | Rs. 50,000 | Rs. 36,250 | Rs. 13,750 |
| Rs. 500,000 | Rs. 86,000 | Rs. 70,250 | Rs. 15,750 |
Who it affects, and what the speech does not say
Tech employees and salaried founders paid a monthly salary and allowances will see the change on that employment income from 1 April 2027, if the new bands are applied as Annexure V describes. The annexure revises “the income tax rate structure of individuals,” so the bands are not described as employees-only. Bonuses, share income and dividends are not mentioned here.
The official speech is silent on a distinct freelancer regime, and silent on a special income-tax rate or exemption for foreign-currency service income. Annexure V, paragraph 7.4, will amend section 73 of the Inland Revenue Act so that the source of income from remote and digital services, including online advertising and cloud services, is determined “by reference to the place of payment.” That is a source rule, not a rate cut or an exemption.
VAT for startups invoicing in foreign currency
This is a VAT valuation rule, not an income-tax change. The official speech (printed page 76) proposes to use the Central Bank’s Indicative Exchange Rate “for the conversion of foreign currencies into Sri Lanka Rupees for VAT purposes” on “taxable supplies denominated in foreign currencies.” The Commissioner General of Inland Revenue “will specify by way of a circular” how the rate is to be applied. Annexure V, paragraph 2.5, says the same. At 6:12 PM Asia/Colombo, Newswire used the broader phrase “foreign currency transactions,” and “application guidelines.” Neither 36.6 nor that update gives a start date. Annexure I lists “Revision of Value Added Tax” as effective in April 2027; Annexure V’s general rule is 1 April 2027 unless otherwise stated. Wait for the CGIR circular before changing invoicing practice.
What founders should do now
If you pay yourself or staff a salary, recalculate take-home pay from 1 April 2027 using the official annual slabs, and wait for an official notice before changing payroll software. If you invoice in foreign currency, wait for the CGIR circular; do not treat it as an income-tax exemption. The official speech is on the Treasury site.
What we still don’t know
We do not yet have PAYE coding guidance, the gazette text, or the CGIR circular on how the indicative rate will be applied. Written after the official English speech PDF was opened, and after Newswire’s 6:07 PM and 6:12 PM updates, on 12 November 2026.
Sources opened on 12 November 2026: official Budget Speech 2027 PDF from treasury.gov.lk (https://www.treasury.gov.lk/web/budget-speeches/section/2027; file https://www.treasury.gov.lk/api/file/ea495202-fcb1-4c78-b34e-58389cb20738), English text printed pages 74 and 76, Annexure V (printed pages 91, 93 and 95–96) and Annexure I (printed page 83); Newswire live updates, 6:07 PM and 6:12 PM Asia/Colombo. The monthly tax table is calculated from Annexure V’s annual slabs under the assumptions stated above. Not legal or tax advice.